Are OCIOs’ Private Equity Allocations Reaching an Inflection Point?          

October 1, 2026

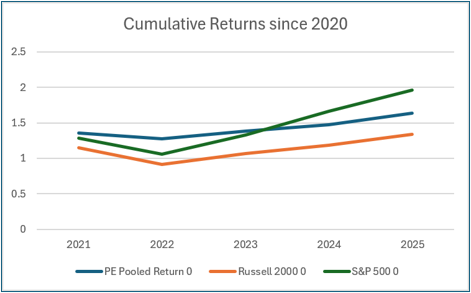
Much has been said about disappointing PE fund returns when compared to public market returns over the last four years.  We have seen a real slowdown in PE returns, especially versus the S&P 500, and a prolonged slowing of PE Funds’ capital distribution rates adds questions about whether PE carrying values are actually accurate. 

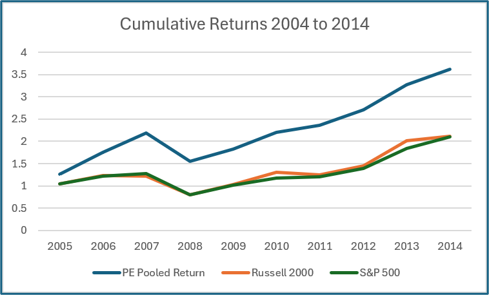
Investor belief in the sustainability of their PE programs often seems to rely on the longevity of their experience.  As you can see from the graphs below, investors with over 20 years’ PE allocation experience remember the great performance of PE compared to public equities.  From end-2004 to end 2014, the return of the average PE investment, as measured by Cambridge Associates, was about 260%, compared to the index performance of both the S&P 500 and the Russell 2000 of only about 110%.  However, from end-2020 to end-2025, the S&P 500 returned about 96%, while the PE average returned only 63%.  Small cap equities performance was meager, up only 33%. 
Is the relatively new weakness in PE returns a temporary deviation or indicative of a long-term pattern?  Does the long-term investment thesis of PE managers still hold, that an abundance of small companies could benefit from the resources brought to them by PE firms? Is the potential to create value from having a private equity manager to manage a company both professionally and privately is compelling?

Checking assumptions

As an Economist by training, I like to look further for indicators of economic drivers.  We understand that higher interest rates have hurt PE investments because PE managers face higher financing costs over the last four years.  We also understand that PE funds have tended to invest in sectors that have not kept pace with the broader market, like potentially legacy SAAS businesses, and away from cloud computing or AI businesses.

But the central question is whether PE managers can still see promising opportunity sets for future investments.  If there are great, untapped opportunities, then PE investing could look very favorable and investors should sustain their allocation programs.  Conversely, if there are limited opportunities available, would it still be reasonable to expect PE managers to outperform public equities?

The private investments industry has an obsession with analyzing returns.  Looking through the Q1 2026 Cambridge Associates Private Equity Index and Benchmark Statistics Report, I see a wonderfully detailed compilation of carefully calculated statistics by a truly dedicated leader in private investing.  What is missing in this excellent 112-page report?  The most obvious statistics: the “total allocation” of assets invested and outstanding each time period.  Not to single out Cambridge, since Pitchbook and Preqin reports also seem to miss highlighting this data as well, though I’m sure all three data providers have compiled that data.

Let’s look at quantities invested in PE, thinking about an analogy to fishing boats.  If there are very few fishing boats in a bay, they can pick the best fishing grounds with ample catches.  Conversely, if there are many fishing boats, they may face waters crowded with other boats and see much smaller catches.  So where do PE managers compare to these fishing boats?  Are they facing an abundance of opportunities?  Or is their market crowded with competitors and diminished catches?  One indicator would be the ratio of PE funds under management [number of fishers] to the overall small cap equity market [as a proxy for volume of fish to catch].

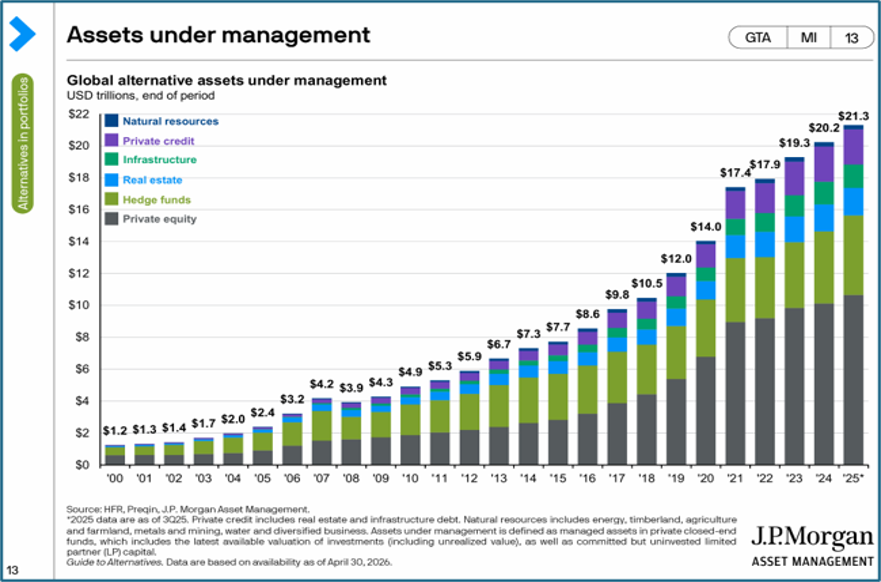
J.P. Morgan Asset Management’s Q2 2026 Guide to Alternatives (See CHART I on the last page) estimates that PE represented about $10.5 trillion globally at year-end 2025, up from about $9 trillion at the end of 2021, $5.5 trillion in 2019, under $3 trillion in 2015, and $2 trillion in 2010, and under $1 trillion in 2005.  Let’s compare those figures to the size of the Russell 2000 market over time:
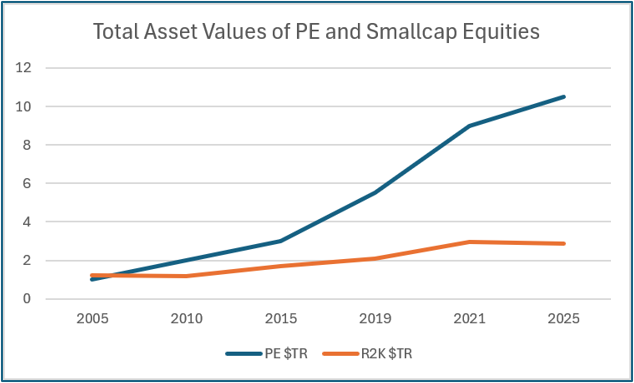
The relationship between private equity markets and small cap equities has clearly evolved.  First, we see PE investments stifling the growth of small cap equities, acting as a substitute source of capital.  Our prior research on small and microcap public companies indicated that regulatory costs could consume over 5% per annum of ROE for smaller companies, so there is a direct economic advantage to being privately held if a firm is small enough. 

Second, if private equity managers were looking to small cap equity companies or IPOs as a source of exits, that has clearly become more difficult to expect, with the small cap market at only 30% of your market’s size.  Conversely, if you can accept the size of the small cap market as a proxy for your opportunity set for buying new companies into your portfolio, it is clear that you are facing over harvested fishing grounds.

The comparison I selected is very simplistic.  PE firms are mostly buying private companies, not so much taking small cap companies private.  Nonetheless, the size of the market of private companies not already invested in by private equity funds I would argue has become much smaller, though I do not have data on the remaining ex-PE private company market.  Another simplification is that I used the global PE market size, of which about 1/3rd is ex-U.S., so the graph above mildly overstates the problem.  Even so, I think the comparison indicates that PE firms are more likely to struggle to find exits, since the pool of potential buyers from publicly listed companies interested in their businesses is greatly depleted.  Sales to other private equity managers, secondary funds, or other means that lack the pricing transparency of public markets will rise in importance, but these methods do not match the historic expectations of institutional investors for transparent exit means. 

Conclusions

PE investments have historically provided attractive returns, but a crowded market with diminished investment exit routes might bring an end to the “era of alpha” from the “asset class” of PE.  We believe that PE brings diversification benefits and opportunities for excellent returns, but should be looked at more from the perspective of a sector-driven lens than in the past. 

Some OCIOs could be missing some of the best opportunities by focusing on very large managers and avoiding the below-$1 billion private equity managers.  OCIOs should concentrate on their better PE managers, and have a clear investment thesis.  They should also be careful of additional work that arises from the growing use of continuation vehicles, which require diligent OCIOs to understand underlying portfolio companies, not just the PE manager.  Continuation vehicles also call for OCIOs to be ready with an investment thesis on each underlying portfolio holding, so they can decide whether to take the liquidity or roll their investment over into the new continuation vehicle. 

Thus, we see a continuing role for PE investments in institutional portfolios. However, having such investments is becoming more of an ancillary addition than a core allocation necessity for sophisticated institutional investors.  Moreover, the effort involved in allocating to private investments is increasing, as OCIO analysts must now cover underlying investments in their PE funds, so they can be ready to decide quickly whether to participate in secondary sales and continuation vehicles.  These difficulties could lead to OCIOs gradually reducing the amounts they commit to PE funds.

In conclusion, we are seeing a changing role for PE at OCIOs.  Prioritizing private equity investments was seen as a top priority as recently as four years ago.  The discussion is more nuanced today.  We see some OCIOs actually pulling back on their PE recommendations as public equities have mostly outperformed private equities, while others sustain their commitment to the PE “asset class,” and expect both returns and distribution rates to recover to their long-term profile of outperformance. Many OCIOs are also enjoying a resurgence in alpha creation from their hedge fund managers, while seeking other ways to product alpha beyond private equity markets, so their reliance on PE investments has somewhat diminished.

We view 2025 and 2026 as an inflection point for Private Equity at OCIOs, moving away from a solid growth trajectory.  We see the potential for a meaningful long-term decline in traditional private equity investments at OCIOs, but we also see private equity remaining a core piece of many OCIOs’ model portfolios.

Chris Cutler CFA

President

Manager Analysis Services, LLC

CHART I
PRIVATE EQUITY SECONDARY FUNDS AND THE INVERTED J CURVE

One of the main challenges institutional investors and OCIOs face today is ensuring longevity of favorable returns from their private equity and venture capital investment programs.  Following 2021, both returns and distributions/returns of capital from those investments have fallen sharply.  We have written about the return challenges in prior Briefings that are posted on our website www.manageranalysis.com.  In the last year, distributions/returns of capital have started to increase which could be seen as favorable.  However, we believe that over 1/3rd of all distributions now come from events where the private equity manager [the GP] retains their control of the companies sold, using continuation vehicles or GP-led secondaries.  Adjusting for these GP-led efforts, “true” exits may actually be continuing to decline.

This Briefing continues our exploration of key themes in private equity and venture capital allocations, where Secondaries funds offer an alternative way to invest in privates.

I. Private Equity Secondaries require a closer look

Many investors have now asked us to opine on various fund offerings by Private Equity Secondaries funds.  These funds have become incredibly popular investments over the last few years with assets currently invested at $700 billion, “dry powder” of $300 billion in 2025 and fundraises of $120 billion in 2025 according to Pitchbook’s 2025 Global Private Markets Fundraising Report. For asset owners that are new to private equity, secondaries funds may also offer immediate diversification across managers, sectors, and vintages. 

A typical pitch to asset owners is that the new fund has a premiere private equity secondaries manager running it with great access to attractive assets for sale.  Most compelling, the new fund already has a very high IRR, and prospective investors historically appear to respond to that enticement by subscribing before the fund’s subscription period ends.

Marketing in Private Equity Secondaries frequently contains obfuscations that are important for investors to identify and understand, and we assist investors in that effort.  In some cases, we find compelling opportunities, but in most situations, we advise against these investments.  One of the most critical hurdles is that the private equity secondaries manager should add more value than their management and carry fees.  We usually think of those fees cumulatively costing 8 to 10% of the value of a secondaries fund over their full life, which is a high hurdle to cross but one that good managers have been able to do.

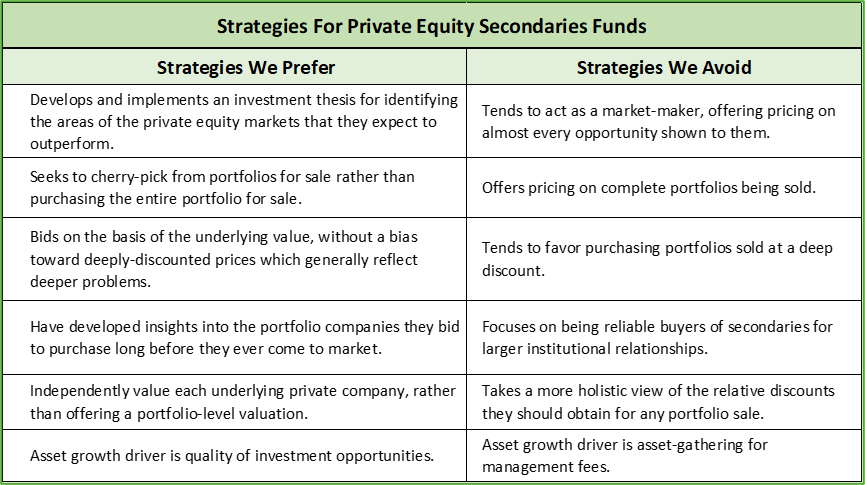
Key facets we like or avoid are:

We believe that, to assess the investment opportunity of a private equity secondaries fund, it is important to understand the dynamics of the “Inverted J Curve.”

II. Explaining the “Inverted J Curve”

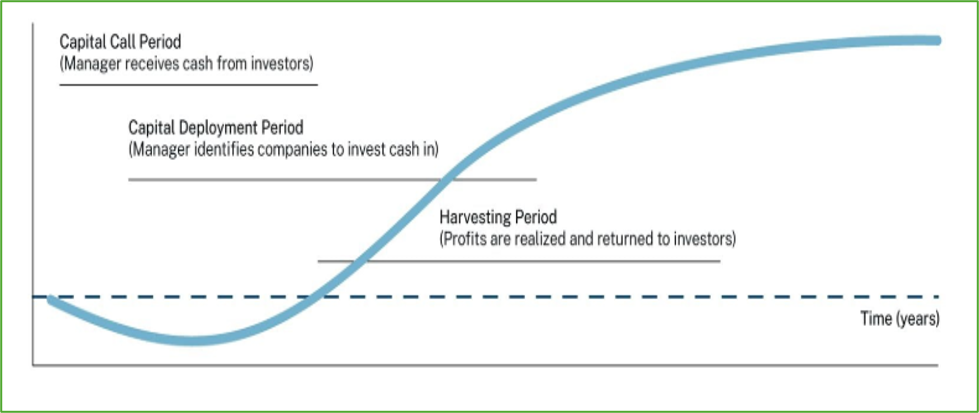
The J-Curve occurs in private equity investing, where the private equity manager acquires portfolio companies while typically incurring large upfront diligence and restructuring costs for the acquired companies.  Initial returns may be low or even negative for the first few years, but usually rise sharply when the fund is fully invested and portfolio companies’ earnings improve under the private equity manager’s supervision.

Source: Hamilton Lane Knowledge Center

The “Inverted J Curve” for private equity secondaries reflects the awkward and problematic utilization of the “practical expedient” accounting method, which is the most common valuation practice used for private equity secondary funds. It simply accepts the value stated for each underlying fund investment, as provided by each of the fund’s many private equity managers.  Thus, if a private equity secondary fund purchases a $10 million fund investment at a 30% discount for $7 million, the accounting practice is to recognize that $3 million discount as an immediate gain.  Since most private equity secondaries are purchased at a discount to their stated value, the net result is that new private equity secondaries funds will demonstrate a very high initial IRR.  That IRR will usually go down over time, as the private equity secondaries fund becomes fully invested and no longer realizes these instantaneous gains, and as reasons for the initial discount like application of secondaries fund fees and weak performance of holdings manifest themselves.

The real challenge is that the discounted prices often reflect actual weaknesses in the underlying holdings or their managers. Over time, the example of a 30% discount may cause future returns to be, for example, 6% lower than the average private equity fund over roughly 6 years.  Adding to this future drag on returns is the second layer of fees that private equity secondaries managers charge investors.  The net result can be a substantial under performance compared to other alternatives the investor could achieve elsewhere.

Relying solely on IRR calculations to understand private equity secondaries’ managers’ performance is fraught with hazards, the biggest of which is that funds that use the ”practical expedient” accounting approach.  This approach implicitly assumes a full recovery of discounted values, while ignoring potential problems with underlying holdings that caused the discounted valuations in the first place.

Following are some anonymized examples we share from our research on behalf of clients. Of serious concern for investors is that some of the state returns we examined are substantially inflated: when we compared the IRRs investors received with the IRRs stated in the funds’ marketing materials, we found the actual IRRs can be 3% to 5% per annum lower.  Treatment of leverage, timing of investment cash flows that do not align with capital call dates, and treatment of refunded capital calls all appear to favor IRR inflation in reported fund performance data without benefiting actual cash returns.

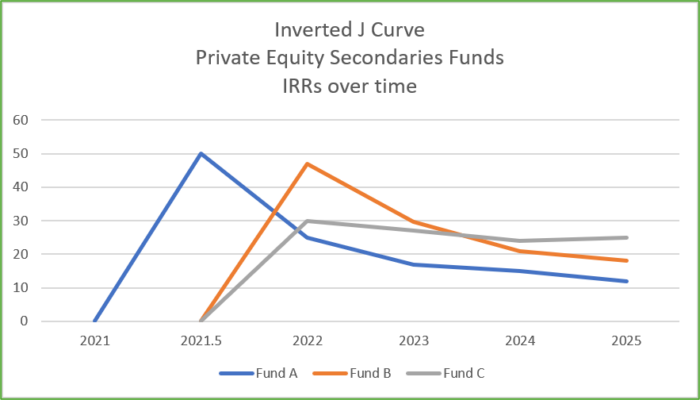
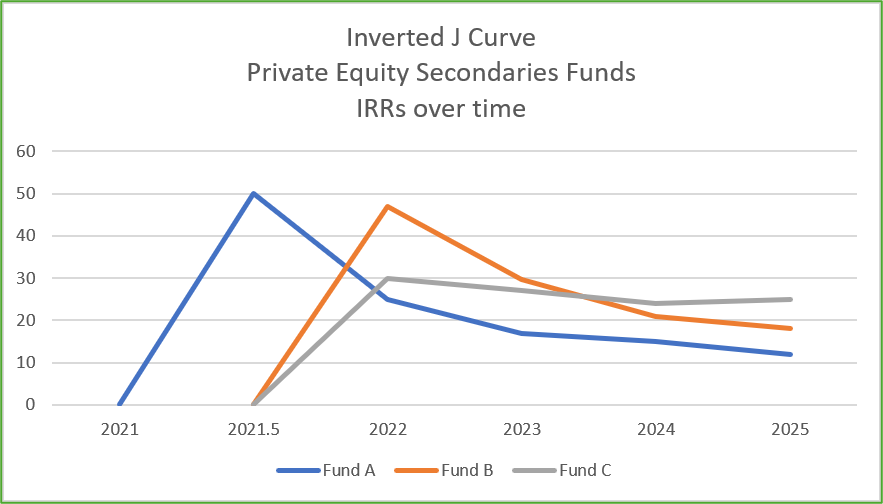
The following graph reflects anonymized, indicative performance, derived from of three private equity secondaries funds we initially examined five years ago:

Fund A performance is derived from a fund managed by one of the very largest private equity secondaries managers in the marketplace.  Their use of the “practical expedient” practice is obvious in the first year of Fund A’s performance.  Since the fund was then still open to new investors, the manager could seek to impress prospective investors with the very high initial return.  After the strong first year return, the average annual return of Fund A was actually close to zero, with the ultimate 11% IRR through 2025 almost entirely reflecting the first-year gain.

Fund B performance is derived from a fund managed by a value-focused boutique manager. Their use of the “practical expedient” accounting is also obvious, but future returns are much better, and they outperformed Fund A by about 7% per annum.  Fund B’s manager focuses on cherry-picking to acquire interests in stable, well-capitalized private businesses with strong fundamentals. Their approach is allowing them to miss the SAAS-apocalypse and they continue to perform well. 

Fund C’s performance history differs in that Fund C avoids the enticement of the high initial IRR print.  Fund C does not use the “practical expedient” accounting method and instead amortizes the discount over an expected life of the holding.  They also take a more active role in valuing each holding to override reporting provided to them, if Fund C’s manager’s value is lower.  Fund C’s manager is a very large private equity manager that seeks to understand all of the underlying portfolio companies.  Before a secondary private equity portfolio is shown to them, they already have performed meaningful diligence on the majority of private companies in the portfolio, and know each of those companies’ management teams.  Their approach causes them to pass on many opportunities shown to them, so they can focus on where they are seeing better opportunities.  Fund C’s five-year returns are twice the returns of the “asset-gatherer” Fund A, reflecting Fund C’s manager’s prioritization of investment diligence over asset gathering, which is reflected both in their fair valuation approach and excellent investment returns.  

III Conclusion

Understanding performance drivers and management philosophy in private equity secondaries markets is just as important as in other alternatives markets.  Nonetheless, we continue to be surprised by the dominance of “asset-gatherer” managers in attracting investor assets into private equity secondaries funds, while using the very misleading “practical expedient” accounting practice.  We expect many investors to be disappointed by their secondaries allocations, while diligent and skillful investors will achieve satisfactory results. 

Should you wish to discuss assistance in due diligence of a secondaries strategy, review of an OCIO, or just want a second opinion, please call us at 917-287-9551 or email us at cutler@manageranalysis.com.

The analysis presented here is the sole opinion of Manager Analysis Services (MAS). Any investment decision should be made with reference to one’s own risk and return objectives and in counsel with one’s advisers.