Outsourced CIO or Not? How an IC Might Approach the Decision

Let’s explore how an Investment Committee may approach the decision in an organized process:

a) Your Range of Available Alternatives
b) Key questions to Consider
c) Obtaining Buy-in from Your Fellow Committee Members
d) Educating Yourself on the Advantages/Drawbacks
e) Ensuring a Focused Comparison of Providers
a) Your Range of Available Alternatives

The typical continuum of Investment Management approaches are as follows:

Certainly, there are variations of the above four approaches including a hybrid of approaches.
While each approach has the potential to succeed, there are approaches that contain inherent
structural and behavioral flaws which may impede success. (One could also split the portfolio
corpus between internal CIO and outsourced CIO management.)

In an AGB publications1, they “strongly advise against…the investment committee [that]
functions as CIO, often with the help of a consultant…we now have decades of strong evidence
that Investment Committees simply have found it difficult to succeed in this role2 .”
If we accept the results of the AGB research, then we are left to focus on Internal CIO, IC Chair
as CIO, and Outsourced CIO. Internal CIO (and staff) introduces the issues of cost, economies
of scale, and compensation/personnel issues. IC Chair as CIO concentrates power and discretion
in a single person, who is a volunteer. It may work if the person has the required expertise,
leadership experience, and the time to focus. Let’s now turn attention to the focus of this
briefing, how to consider an Outsourced CIO.

b) Key Questions to Consider

Let’s consider whether an Outsourced CIO may be appropriate for your organization. Before
considering the merits, some threshold questions are appropriate:

  1. A non-profit typically retains outside legal counsel, external auditor, IT expertise, payroll management, grant tracking, etc. (all non-core activities) where external expertise is needed and a recognized value-add. Do members of the IC view an Outsourced OCIO as a value-add and are they willing to give up day-to-day investment control and shift their focus to oversight and more strategic issues?
  2. If the Board is open to an Outside CIO, what are the existing and future challenges/issues that the committee is trying to address?
  3. What are the range and type of desired investment offerings that need to be provided by the Outside CIO?
  4. How should the Committee members educate themselves as to what’s available, what’s appropriate for their organization and how can they effectively and efficiently internalize the information to arrive at the best outcomes for their organization.

(Certainly, there are more detailed and other helpful questions that will assist a committee
in its analysis, but we shall consider only those above for purposes of our review here.)

c) Obtaining Buy-in from Your Fellow Committee Members

Research has shown that non-profits, with rare exceptions have simply not maintained the
purchasing power of their Investment Portfolios, especially relative to the pre-GFC (2007)
levels.3 In order to conduct an effective Outsourced CIO search, the IC members must first agree
that there is a challenge to be addressed. If there is disagreement on the IC as to which of the
four main approaches presented are appropriate, the search process may be fatally flawed and
simply not lead to the best outcome. It may well further divide the IC if the differences of
opinion are not subject to suasion or authentic consensus.

If authentic agreement can be reached to move forward, then the IC should be specific and agree
in writing, on the precise parameters of who should have what investment management
responsibilities and the proper assignment of oversight duties.

The IC should agree on what gaps or deficiencies are to be addressed. They should review their
existing IPS and see if it really addresses how they would like the portfolio to be managed on a
go forward basis. This is the time to identify asset classes, investment structures (e.g. comingled
accounts v. SMA’s) that the IC wishes to embrace or avoid. If there is a desire to focus more on
impact investing or ESG, this is the time to identify that as an item of inclusion, as well.

d) Educating Yourself and IC on Advantages/Drawbacks of an Outsourced CIO

An Outsourced OCIO is no panacea but a means to an end. Given the customized demands of
individual non-profits, you need to understand what your wants are and what is available or
customizable in the market. There is abundant information available on provider websites and
some can be quite useful, and while much may not be directly on point for your needs. You
could invite a sample of providers to address your IC at periodic meetings and gradually obtain
key points of information, but the information may be skewed or incomplete.

In the alternative, it may be more cost effective and time efficient to hire a search consultant who
can match your specific needs to what the outsourced CIO providers offer and what could be
created for you. Be mindful that there are 80+ OCIO providers who assert national coverage and
yet they have quite different investment approaches, investment vehicles, asset class coverages,
reporting capabilities, fee structures, gradations of outsourcing services provided, etc.

You also need to achieve a “good fit” with your ultimate provider. This will maximize your
chances of forming a long and worthwhile partnership with your provider. A search provider can
provide a team who gets to know you and can partner with you to achieve your specific goals.
The team will be your strongest advocate throughout the search and the on-boarding process.

e) Ensuring a Focused Comparison of Providers

Although the industry has grown to $1.1Trln4 over the last 20 years, it suffers from a lack of standardization in reporting returns and some opaqueness as to total fees charged. There are a variety of OCIO firms each with their own areas of strength. The lineup of providers includes a) the largest OCIOs with +$90 Bn in AUM, b) medium-sized OCIOs who are considered the $15 – $30 Bn range, c) niche OCIOs who have a specific investment strategy focus, and 4) alternatives-focused OCIOs. If the Committee does not have a consensus view as to the type of OCIO they would like to work with, seeing a variety of OCIO models and reviewing the services obtainable from each would help the IC arrive at a more informed decision.

An additional caution is that once an Outsourced CIO is chosen, then portfolio assets will likely
need to be liquidated and/or transferred to new custodians. There are risks involved with this
timing and asset transfer. It should be planned in specific detail to ensure that there is no market
timing or excess bid/offer spreads incurred. Without enough planning and oversight, losing 30 –
80 bp’s on the portion of the portfolio liquidated can occur. There could also be legacy assets.

Summary

In summary, the goal is to ensure the IC fully describes what its needs are and what level of
discretion suits its members. If there is not agreement by the IC members PRIOR to the actual
search, it will be likely be more difficult to achieve the best outcome possible for a non-profit
organization. There are a broad variety of providers whose specific expertise and structure
enables them to provide solutions best suited to some types of clients rather than others.

Want to learn more? Please contact Chris Cutler, Tom Donahoe or Safia Mehta at 917 287 9551.

1 Association of Governing Bodies of Universities and Colleges, “Endowment Management for Higher Education”, 2017, AGB Press, Washington, D.C.

2 They cite 4 impediments: Lack of expertise, difficulty in making timely decisions, inability to make difficult, contrarian decisions, and diffusion of responsibility., ibid., p.25

3 Sandeep Dahiya, David Yermack. “Investment Returns and Distribution Policies of Non-Profit Endowment Funds.” Report 11/27/2018 Available on https://papers.ssrn.com

4 Cerulli Associates/Blackrock, “OCIO at an Inflection Point”, P. 3, Report 2019 © 2019 MAS, LLC

Foundations And Endowments Find Help For Navigating Complex Outsourced CIO Market

By Colin Rajala I September 5, 2019

Mark Titzer joined Dominican University as its VP for Finance in May, 2017, with an extensive to-do list from financial strategy and budgeting, to rebidding all of its contracts and services. As more pressing day-to-day tasks and operational matters came across his desk, the task of rebidding contracts seemed to be falling down the pecking order like the stock market after an interest rate hike.

Titzer’s staff of six had just as much on their plate, and the task of rebidding its outsourced CIO contract seemed years away, especially with the increased sophistication of investment portfolios and the complexity of outsourced CIOs and their various institutional models.

Those barriers led Titzer to contract a search consultant to help navigate the outsourced CIO rebidding initiative of reviewing and evaluating the options available, for a firm to manage its approximately $35 million endowment.

‘We didn’t have the expertise or the time to do justice to the process,” he said. “We knew we weren’t going to be able to ask all the right questions and do a proper comparative analysis … It was a no brainer to work with a search con­sultant for the due diligence and independent review process.” Titzer and his team are not alone, and with the outsourced CIO industry expected to grow by 10.7% among nonprofits between 2018 and 2023, according to a report from Cerulli Associates on behalf of BlackRock, more foundations and endowments are likely to turn to search consultants to assist with navigating what can be a difficult evaluation and search process, according to investors.

“I think the prominence of outsourced CIO search providers coincided with the growth of outsourced CIOs in the last six to seven years,” said Frank Wilkinson, managing director of North American Marketing at outsourced CIO, SEI Investments. “Then there were probably in the realm of 50 or so companies listing themselves as OCIOs, and that has jumped to more than 80 currently. In the end, it is up to the institutional client to explore their options, but that has become more and more difficult with so many variables and options available to them, so they have increasingly looked to outside help to assist in the processes.”

Outsourced CIO options can range from large multifaceted financial institutions with an investment function, to large investment consulting practices with an outsourced arm, to smaller boutique investment firms, and determining which model is the best fit for institutions is a key reason for the increased usage of search consultants.

lnHub, which provides an on line RFP technology, has found that greater than 60% of discretionary endowment and foundation RFPs on its platform have a search consultant running the process, as opposed to the less than 20% that use a search provider when seeking traditional consulting services, according to Ariana Amplo, Founder and CEO of lnHub.

Beyond the variety of options and mod­els for nonprofits to understand and tra­verse, the lack of resources, smaller staffs and infrequent board and committee meetings has also pushed some to utilize the search providers.

”They just can’t do it themselves, they just don’t have the bandwidth,” said Tom Donahoe, Managing Director of Outsourced CIO Search and Governance at Manager Analysis Services. ”There are many talented people on the committees and boards, but you only have a certain amount of a governance budget, or the time and focus to fulfill your fiduciary duty. If the committee members quit their day jobs, they would certainly be able to undertake a full-blown search by themselves. What they realize is that they can’t quit their day jobs, they only meet about four times a year and they really can’t respond as nimbly as a fiduciary as they would like.”

Connecting With Search Providers

Foundation and endowment forays into the outsourced CIO space have been most prevalent among institutions below $500 million in assets, according to investors and allocators.

The average asset size of an endowment and foundation conducting a discretionary manager search on lnHub’s platform was just $52 million in 2019 compared to approximately $137 million in 2018, according to Amplo.

“As more smaller endowments and foundations adapt RFPs, there are more opportunities for managers to bid in a formal process for these. It is not only a process reserved for large accounts anymore,” she said.

Investment advisor North Pier Search Consulting has worked with orga­nizations with roughly $25 million in assets, but finds its sweet spot to be those with assets of $75 million to up to the high hundreds of millions, said Managing Partner, Founder and CIO James Scheinberg.

“We are focused on the small- and mid-sized organizations, frankly the organizations that originally would not have the ability to use the firms that charge more to do large OCIO searches,” said Larry Coats, Jr., President and CEO of Clearview Fiduciary Alliance, a membership-based service that facilitates the sharing and reporting of nonprofits’ investment advisor and consultant results to help the institutions understand and analyze their investment programs. The alliance currently consists of 41 member organi­zations totaling $1.2 billion in long-term assets with the members ranging in size from $1 million to $245 million in assets, according to Coats.

He noted that the organization only does searches for nonprofits that agree to be members of the organization, saying, “We want to see that they are committed not only to a project to find hopefully a good or better advisor than what they have now, but we want to make sure they are doing that in the context of making a long-term commitment to be better fiduciaries and be better informed fiduciaries.”

While smaller organizations appear to be the most prevalent user of the search provider resources, how the institutions connect with the providers is often by chance or through their small networks, according to investors and allocators.

“When you are doing a search for an OCIO search provider, having to search for an OCIO search firm is adding another level of complexity to the process and it doesn’t really happen too often,” said Chris Cutler, founder and manager of diligence and outsourced cio search at Manager Analysis Services. “What we are seeing, and we don’t think this is efficient, is that people are approaching outsourced CIO search providers because they are associated with a large brand or because of a personal relationship a board member already has with an outsourced CIO search firm.”

Dominican University’s Titzer was not aware of what firms might be able to help with a search as he was looking to rebid its contracts. He was for­tunate to come into a situation where the institution was working with an advisory firm, Plan PILOT, that was providing fiduciary advisory services for the university’s 403(b) retirement plan.

The finance team was going through a set of quarterly training sessions with Plan PILOT’s fiduciary team to make sure the team was meeting its responsibilities before he asked if they could, or knew anyone that could, help with an advisory search for its endowment.

“It was an off-handed ask if they do that type of work. It wasn’t something we went after immediately,” Titzer said, noting that Plan PILOT Managing Director Mark Olsen and Senior Consultant Frank Szymanek were thorough in their process and able to ask all of the right questions to align staff, trustees and its outsourced CIO.

For institutions that are looking for search consultants or outsourced CIO providers outside of their networks, a good place to start is attending industry events and conferences, according to CFO Jack Willoughby at the First Community Foundation Partnership of Pennsylvania. He noted that the foundation did not utilize a search consultant as part of its rebid process in 2017 /2018 as he compiled a list of outsourced CIOs years in ad­vance of the search by fielding calls from any and all providers to become familiar with the services and models available.

Through his own research, he knew the various outsourced CIO market seg­ments and his organization’s need for a firm with a strong research team. Willoughby asserts that nonprofits that are not familiar with the discretion­ary manager space should not be hesitant to identify an unbiased opinion to corroborate their own conclusions.

That sentiment was echoed by CIO Bruce Guiot of the Miami University Foundation (Ohio), which tapped Botanica Capital Partners to help con­duct an invitation-only search for an outsourced CIO that wrapped up last year.

“Most folks by then had heard of the OCIO model, but did not fully under­stand what it means or certainly the ways it gets delivered,” he said. “We needed someone to educate the board impartially … The consultant was initially brought on to evaluate the ‘buy versus build decision.”‘

Connecting with search providers is not reserved solely for institutions, as outsourced CIOs should also be net­working with the search consultants to ensure they are aware of the discre­tionary firms’ management team, processes and philosophies.

“As we have grown the business and expanded, we have broadened our sights of the [search] consultant market,” said Matthew Wright, President and CIO of outsourced CIO Disciplina Group. “We brought on [Managing Director] Brian Arsenault to help those efforts and look at search consul­tants to understand who is in the marketplace and expand our reach to meet with them. Four or five years ago it was not something we focused on. Back then, opportunities surfaced from a committee or staff member who was going to lead the change and we would try and meet them or have someone set up an introduction.”

SEl’s Wilkinson noted that the outsourced CIO firm has historically had resources dedicated to lead generation outside of traditional direct chan­nels, such as referral opportunities, and it has been a natural evolution for them to focus on search consultants.

“We have a dedicated practice within our institutional group committed to serve as intermediaries between SEI and the search providers,” he said. “They are independent of direct sales responsibilities and can focus on helping build relationships with search consultants. It was driven by the need to build relationships and drive education on who we are and what we provide.”

As institutions and outsourced CIOs look to build connections with the search providers to help them navigate their search initiatives, the search consultants can distinguish themselves from peers through their own connections to the outsourced CIOs and qualitative information about the firms, according to Donahoe.

“When people do an outsourced CIO search, they don’t know the backstory for any number of the organizations,” he said. “We differentiate ourselves in our intimate knowledge of these firms. Who is in the driver’s seat? How long are they going to be there? What changes at the firm have occurred and what are their motivations? We incorporate these insights in our workings with the board so that they better understand what each firm has to offer and to enable their decisions to be fully informed.”

Search Consultant Processes

Many nonprofits, particularly on the smaller side, are board-driven or have a staff that is more administrative than investment-focused, which often means they do not have the requisite skills when it comes time to select an outsourced CIO or evaluate performance, according to investors and allocators.

“These organizations are only sitting from their vantage point. They don’t see the field like we do,” North Pier’s Scheinberg said.

Nonprofits have historically struggled with investment advisor RFPs be­cause of the lack of requisite skills, according to ClearView’s Coats.

“They didn’t have a process, it wasn’t logically established,” Coats said. “They would call another organization that did an RFP in the last five years and say, ‘would you give me a copy of what you send?”‘

The inability and difficulties surrounding organizing and executing suc­cessful RFP processes has provided an opportunity for search consultants to show their value to institutional investors. Scheinberg finds that con­structing an RFP, providing answers from respondents and constructing a scoring grid is “a baseline service that everyone should be doing.”

“Having institutional quality oversight over the selection and monitoring of an OCIO provider is critical to meeting the institution’s financial goals and their fiduciary responsibilities. Retaining a search consultant, perform­ing a thorough RFP, and utilizing automated solutions, are part and parcel of an effective governance process,” said Plan PILOT’s Szymanek.

The search processes often begin with search consultants focusing on the organizations themselves to get a better idea about their goals and missions and what they are looking to achieve from an outsourced CIO relationship.

“It is similar to a marriage. We are trying to really understand the board, its investment philosophy, and their specific goals and needs,” Donahoe said. “We engage the members direct­ly and work with them to verbalize and document what their ideal outcome would be.”

Scheinberg said North Pier carries a similar approach, saying, “We spend a lot of time at the initial stages, not just getting to know the organization’s needs, but we literally sit down and do interviews with every single committee member.”

Clearview takes a varied approach in the early stages of the process, instead focusing on the institution’s investment policy statement and ad­dressing issues such as asset allocation, benchmarking, governance roles and responsibilities.

“One of the primary objectives of the investment policy statement is to clearly and specifically define and communicate responsibility, authority and accountability,” Coats said.

From there the search consultant or institution will typically issue an RFP to potential candidates directly or to the broad market before beginning the difficult process of evaluating and consolidating responses.

North Pier aims to highlight the differences between the firms to the committee in order to drill down to a shorter list of finalists to present.

“We don’t just hold a dog and pony show. We set the agenda and a recommended amount of time to address the different categories,” Scheinberg said, noting that he and Senior Consultant, Greg Metzger, moderate the sessions and are active in asking questions of the presenters.

Manager Analysis aims to filter through the universe before issuing the RFP to help with alignment, according to Donahoe.

Following the RFP distribution, review and evaluation of proposals, the firm aims to narrow the list of proposals to around five finalists, as they have shown they “can do what is required, will align with the board’s goals, approach and personality, and are not conflicted in any manner,” Donahoe said.

He noted that the firm will go through each potential provider with the board or committee to help them understand what each firm offers and what it is likely to excel at.

“Our manager analysis background brings an unusual set of talent to the due diligence of these outsourced CIO firms,” said Cutler, of Manager Analysis. “I have a strong capital markets background and reviewed over 2,000 alternative investment managers, and the reason that is important is I can come into the meetings and understand whether the outsourced CIO presentations are truthful and credible or not. The integrity of some of these marketing pitches really matches the integrity of derivatives marketing in the early 1990s. You really need to go through and conduct solid due diligence to understand the capabilities, strengths, and weakness of these firms.”

Clearview looks at the candidate pool in four groupings: the incumbent, other firms the organization has a business relationship with, providers recommended by board members based on experience at other organi­zations and, lastly, a list of organizations that submit data to Clearview on behalf of other member organizations. The firm then aggregates responses using the lnHub eRFP portal and prepares a series of reports for committee members to review and score respondents on, according to Coats, who noted that the data is then used to facilitate a conversation and coordinate which firms to bring in for finalist presentations.

Following finalist presentations, the institution is tasked with ultimately making the final selection and entering into the hiring and contract nego­tiation process.

”The ideal outcome is that five or more years in the future, when we have achieved a successful search, the committee is still with the same out­sourced CIO provider,” Donahoe said. ” … Not just because they’ve gotten good performance, hopefully top quartile, but because their goals and philosophies remain aligned.”

He noted that institutions have increasingly looked to the search consultants to help with formalized reviews of the outsourced CIOs every five years or so.

Those periodic reviews can result in foundations and endowments conducting replacement searches, evidenced by 57% of organizations initiating or planning to conduct a replacement search since hiring their outsourced CIO provider, according to the Cerulli report. Of the organiza­tions that have completed the search, exactly half replaced their original discretionary manager, according to the report.

While a majority of North Pier’s clients are looking at the outsourced CIO space for the first time, the firm has begun to see an uptick in organiza­tions conducting replacement searches, as they have a better understand­ing of the services being provided and their respective needs, particularly when it comes to macro level issues, according to Metzger.

In looking at the outsourced CIO market, Scheinberg said North Pier would not hire roughly 80% of the firms claiming to be an outsourced CIO, and that the remaining 20% can be broken out into various buckets based on liquidity appetites, size, style, and ancillary services offered. The firm’s research has found that many of the outsourced CIO offerings coming from firms with traditional general consulting backgrounds, will lag outsourced CIO offering tactical investment strategy by about 120 basis points, ac­cording to Scheinberg.

”The research we have done in these different models has a very different return stream,” Metzger said.

With the outsourced CIO and search provider market flourishing, the cost of the searches comes into question, as everything has a price. Luckily for institutions, the cost to hire a search provider is not as daunting as it may seem.

The typical range for an outsourced CIO search consultant can range between $30,000 and $75,000, with the pricing varying by organization, as well as add-on expenses that arise during the process, according to Scheinberg, who noted that institutions need to ask the right questions and “try and nail down what your expenses are going to be.” He also cautioned about selecting the wrong outsourced CIO as it could cost an institution millions of dollars.

“The fee from outsourced CIO search firms will pretty much pay for itself,” Cutler said. “Fees for the search and selection of an outsourced CIO are not astronomical in any way. If you think of them on an amortized cost basis over the life by which you are going to keep an OCIO, you are talking about a couple of basis points. We may have a dollar price that may look like a lot, but it’s not really that much. If you think about how many outsourced CIO managers we have met, spoken with, and reviewed, you are talking about a huge amount of info you are already gaining access to.”

Dominican University’s Titzer said the search consultant contract price sealed the deal for his decision to hire Plan PILOT to help them rebid the outsourced CIO services.

“There are tight budgets all around here and we don’t have the luxury to spend more on third party firms with­out meaningful results … Even with us not making a change at all, it helped us align the portfolio and reduce costs. The way I look at it, you wouldn’t begrudge a copay at the doctor’s office for a checkup, just like we didn’t begrudge the fees to review our outsourced CIO,” he said.

Disciplina’s Wright notes that while the cost for institutions to hire a search provider are not “prohibitive,” it is another expense that they need to get accustomed to.

“To navigate the landscape, I think institutions need to see what is lost in the cost analysis,” he said. “In that analysis, the cost, whether it is real or mental, is the opportunity cost that is lost in the risk adjusted returns, which can be a large portion of an organization’s operations and pro­grams. Search firms should also aid with fee transparency or true cost. I think that once institutions overcome [that], there will be more growth for OCIO search firms.”

Search Consultant Concerns And Areas For Improvement

As asset management and investment consulting firms have recognized outsourced CIO searches as another potential revenue stream, the firms have added project-based capability to their businesses, which can lead to concerns of conflicts of interest. Those concerns surrounding search consultants are similar to the concerns of conflicts of interest among the outsourced CIO firms they help identify and evaluate.

“I think the space is pretty fair and most search consultants are indepen­dent,” Wright said. “For firms that are wedded to an asset management firm or consultant, the lines can be blurry. I know they say, ‘We have a Chinese wall and no information goes to the other side of the business,’ but the more independence and autonomy of firms, the better it is for the industry. We avoid conflicts in our own business by focusing on one line of business, and prefer search consultants that do the same.”

Most investors noted that conflicts of interest among the search providers have not been an issue to date and continue to emphasize that these firms avoid any gray areas.

“There is still the potential for conflicts of interest where search providers also offer consulting or OCIO-esque services, but by and large our experi­ence has been positive in that the search consultants run fair, unbiased and independent processes,” SEl’s Wilkinson said.

He noted that the search provider space has also helped outsourced CIOs mitigate potential conflicts within their services or implementation, by saying they “have helped clean up that muddiness.”

“If you are a firm that has been reluctant or historically has avoided transparency, chances are now the search consultants will find out. They are asking additional and thorough questions, they are streamlining the process and helping to compare plans the same way, especially when it comes to fees,” he said.

While search providers have helped clean up transparency, there are other facets of the space that they have identified as needing to be less opaque.

“A real limitation we have seen in the outsourced CIO search space, and re­ally across the industry, involves comparability of performance data,” Cutler said. “There are no SEC compliance performance standards, so we rely less on reported historical performance than we would for other types of man­agers. We find many endowment and foundation industry benchmarks may be overstated, so we try to overcome that with our superior analysis of the qualitative aspects of the firms, and getting to know the personnel, how talented they are and how they manage the people and the other aspects of the processes.”

The sentiment was echoed by North Pier’s Scheinberg, who said that the ability to accurately evaluate outsourced CIO performance has been a major problem.

“Left to their own devices, the OCIO won’t show data at a macro level,” he said. “We have to create this data on our own. The industry has the tiger by the tail with this. There is a lot of shenanigans.”

Taking steps to alleviate the issues, North Pier brought 15 of the top outsourced CIO firms together to discuss some data reporting standards during a one-day working group in December, 2018.

“We just think it’s time,” Scheinberg said. “There should be a standard. Organizations 10 years from now should have as easy a time identifying performance on an OCIO firm as they do picking a large-cap growth firm out of Morningstar.”

Outsourced CIOs that have looked to be ahead of the curve, and open about transparency and performance, include Strategic Investment Group, which claimed compliance with Global Investment Performance Standards (GIPS) in 2017. The firm’s decision to become independently GIPS-verified stemmed from the growing demand for clear, quantifiable track records, and to serve as a call to action to its peers to make accurate, appropriate information more accessible to institutions as they review search candi­dates.

Looking to add more transparency into the space, Clearview launched its Study of Investment Fees for Foundations, Endowments and Nonprofits earlier this year. The study, the results of which are expected to be released soon, was conducted to develop a baseline understanding and analysis of the current structure and levels of investment fees incurred by nonprofits, with investment portfolios with assets less than $500 million, and identify the primary variables that impact the investment fees incurred.

Another area where search consultants can aid their nonprofit clients comes during the transition from one outsourced CIO to the next.

“Transition management is an incred­ibly important part of the outsourced CIO process, because once a firm is fired and another is hired, there is a serious gap,” Cutler said. “Foundations and endowments might do a good job finding the right outsourced CIO man­ager, but end up with a bad transition management experience. It’s always someone else’s fault when something goes wrong with a transition.”

Cutler noted instances of assets liquidated during a transition sitting in cash, before being invested slowly over a period of time, which can result in “slippage,” and an institution not being in compliance with their asset allocation goals, as well as losing out on an opportunity to increase assets to use toward its mission.

“That slippage could be 30 basis points on your entire portfolio, or it could be conceivably as much as 70 or 80 basis points when things are really not going well,” Donahoe said. “That is many multiples of the cost of doing a search itself.”

As search consultants have made improvements on the quantitative side of their approach and processes, outsourced CIOs see room for improve­ment on the qualitative aspects of the search processes, according to investors.

Wilkinson has found that the search consultant-led processes have become more formal and structured, in that the lines of communication are very rigid during the process. In his experiences, the outsourced CIO provider, investment committee, and staff do not interact until very late in the search process, with it often concentrated into a two-hour finalist presentation.

“At the end of the day, this is a service industry and service industries are relationship driven … You have to get a feel for a firm to partner with over the next three, five, seven years, so a two-hour meeting is probably not the appropriate amount of time. Moving forward, search consultants can probably improve the process by finding touch points along the way for the OCIOs and the organization to build relationships, which may help the process and the end decision ultimately,” he said.

Another area that search consultants could improve on is easing rigidity in their qualifications and thresholds for the discretionary managers.

Wright noted that when he started Disciplina after managing Emory University and Vanderbilt University’s endowments, outsourced CIOs said the biggest constraint on business will not be size or assets under management, but the number of clients.

“I think that search consultants should factor that into their processes more. The larger outsourced CIOs in terms of assets, number of clients, are very different from the boutique and niche shops like us,” he said. “The larger size, capacity and scale can lead to diminished returns because the service model and returns may get diluted with size.”

Ultimately, the shortcomings of search consultants are outweighed by the benefits they provide to understaffed, resource-constrained nonprofits, as they are “satisfying a real need in the marketplace” and compensating for the “deficiencies in the governance budget” through their formulation of goals and philosophies, RFP construction, distribution and evaluation, according to Donahoe.

“It is pretty clear that search consultants are here to stay,” SEl’s Wilkinson said. “They bring tremendous value to institutions and they are also forcing provider transparency, which we fully support … They are asking additional and thorough questions, they are streamlining the process and helping to compare plans the same way, especially when it comes to fees.”

Disclaimer: Information provided by SEI Investments Management Corpo­ration, a registered investment advisor and wholly owned subsidiary of SEI Investments Company. There are risks involved with investing, including loss of principal. Diversification may not protect against market risk.
Don’t Be Shy! Non-Investment Services an OCIO Can Offer You.

Governance Policies

  1. Periodic, formalized review of Investment Policy Statement (including ESG Investing)
  2. Addressing governance issues and increase efficiency of your Board or Committee
  3. Guidance as to evolving worlds of ESG and Impact Investing
  4. Recommendations as how to overcome any Board dysfunction
  5. Be a neutral “sounding board” for doing things differently or changing processes

Reporting

  1. Providing ad-hoc investment reporting
  2. If some investments are held elsewhere (not with the OCIO, e.g. legacy assets), OCIO may be able/willing to include those positions with OCIO-managed assets and present holistic portfolio summary
  3. Accommodate your special file format needs, e.g. CSV or uploads to secure website
  4. Access to OCIO’s risk portal if it is offered to clients

Accounting/Audit

  1. Provide guidance on special treatment needed for bespoke assets or alternatives held
  2. Help with Audit/IRS requests re: valuation or investment reporting
  3. Assistance if there are concerns about K-1 information/accuracy

Peer Networking

  1. Provide a sense of how peers approach a common issue or provide actual introductions
  2. Obtain information as to salary scales, job duties, size of specific departments, etc.
  3. Invitations to annual/OCIO investor events or industry seminars that may be of interest
  4. Provide research/book/website recommendations

Fund Raising

  1. Introduction to like-minded charities or orgs willing to make grants to the same causes
  2. Meet your donors to assure them that the corpus monies are being prudently invested
  3. Provide future projections of returns and budgets to provide support for a capital campaign

Evaluating/Selling Exotic Gifts Received

  1. Real estate gifts provide a challenge/interim liability between obtaining title and closing a sale
  2. More exotic asset classes such as cryptocurrency create special challenges to liquidate
  3. Art and Sculpture may require special insurance while an exit strategy is planned/effected

Hiring/Vendors

  1. If you wish to get recommendations for an open staff position at your organization
  2. Vendor recommendations (Outside Counsel, IT Security, Grant software, etc.)

The range of ancillary services varies widely across OCIO managers. The ManagerAnalysis.com
team can help you achieve the best match from available OCIO providers to achieve your
specific needs.

Want to learn more?

Please contact Chris Cutler, Tom Donahoe, or Safia Mehta, at 917 287 9551 or 973 452 3992.

©2019 MAS, LLC

Building your in-house Investment Office? What would it cost?

Endowments and Foundations continue to wrestle with determining the best way to manage their portfolios:

  • Build an in-house team?
  • Hire an Outsourced CIO team?
  • Or engage a Consultant Advisor?

Since most Endowments and Foundations (“E&F”) depend heavily on the success of their investment programs, solving this challenge is a key determinant of their ultimate success.

Our research goal was to observe how E&F offices are making this determination, based on their portfolio sizes and number of staff. We focused on the empirical data available for 35 Endowments and Foundations of various sizes. We used E&F’s that had the most verifiable information available in the public domain, reviewing their tax filings, public websites, and LinkedIn profiles to obtain the required information. The data is intended to answer the following four questions:

Key Questions Addressed

  1. If you are planning in-house investment management, how do your staffing decisions compare with what others are doing currently?
  2. What does an In-House Investment Office cost?
  3. Is there a typical AUM transition point where E&F’s might transition between In-House or OCIO Investment team approach?
  4. What are the specific staff roles and org chart characteristics for an In-House Investment Office?

What we learned was both expected and unexpected. Managing an “Endowment Style” Investment Office means managing a complex, private portfolio and a multitude of managers. Yet, the In-House Investment Office size appears to have a definite ceiling.

While the specific facts and circumstances of each E&F investment corpus and each non-profit’s internal structure or requirements are not publicly available, there is detailed information available on key aspects of E&F’s portfolio management. Specifically, we were able to obtain the actual headcounts and the total compensation of the most senior members of each investment team. This is not a scientific sampling, rather it is hard data from a cross section of AUM sizes from $50 mm to $12 Bn. Using this data, the reader will obtain additional perspective as they determine whether building internally or embracing the Outsourced CIO model is the best fit for their organization.

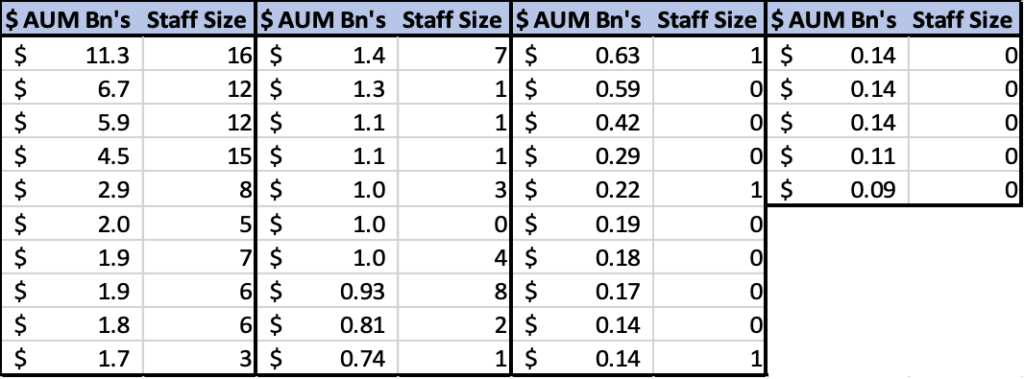
The information on each of the 35 organizations is arranged from largest AUM to smallest AUM. Here are our general observations.

Main Conclusions from the Research

In-House Investment Office

  • >$4Bn AUM generally have in-house investment staffs of 12-16 professionals.
  • $1 Bn to $2 Bn generally have in-house investment staffs of 4-6 professionals.
  • $500 mm to $1 Bn opt for either in-house management or Outsourced CIO.
  • $50 mm to $500 mm often have a single in-house professional or rely on an Investment Committee with/without assistance of a consultant. The sole in-house professional may be more of a liaison and may be focused more on development efforts. (Nearly half of this sized cohort have adopted the OCIO model per industry research.)

There appears to be a tug of war as to whether in-house or OCIO works best in the $750 mm to $1 Bn AUM range. We have seen non-profits grow past the $500 mm AUM and decide that they are large enough to build an in-house team. There have been some notable exceptions recently with some names just below the $1 Bn AUM level. Several have decided to scrap the in-house Investment Office model completely and embrace the OCIO model.

The total team compensation appears to be as follows, based on $AUM size:

  • Mega +$4 Bn AUM – $5 mm to $7.2 mm range
  • Large $2 Bn AUM – $2 mm to $3.5 mm range
  • Medium $1 Bn – $2 Bn AUM – $2 mm to $3 mm range
  • Small x<$500 mm AUM – $300 k-$400 k range

Our total compensation aggregate estimates rely on actual published total compensation numbers for typically the CIO and the next management level, e.g. Director of Public Markets, Director of Private Markets, MD’s, or Sr. Portfolio Managers. The compensation levels for analyst/operations level staff are estimated based on the specific titling/job description obtained. We omit all investment related costs, e.g. Bloomberg terminals, technology costs, office rent, custodial fees, due diligence travel/research, etc. since they vary widely depending on investment strategies. Moreover, the sum of all external investment consultants together can cost well over $1 mm p.a., especially for larger portfolios. Thus, these additional expenses are not immaterial.

Organization of the Remainder of the Briefing

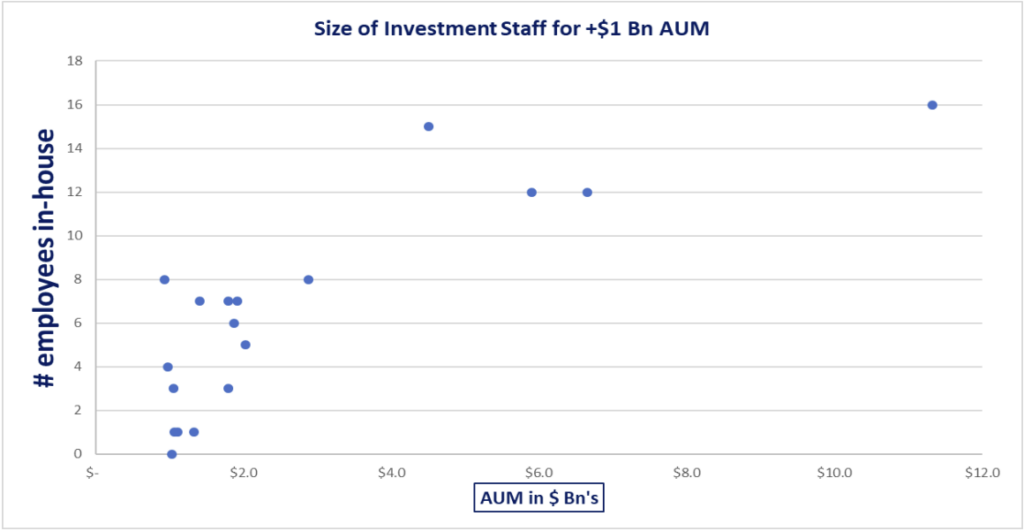
  • Two scatter plots present a comparison of in-house staff v. $AUM. +$1 Bn and X<$1 Bn)
  • Organization Chart for a large >$10 Bn AUM team • Organization Chart for a $1 Bn to $2 Bn AUM team
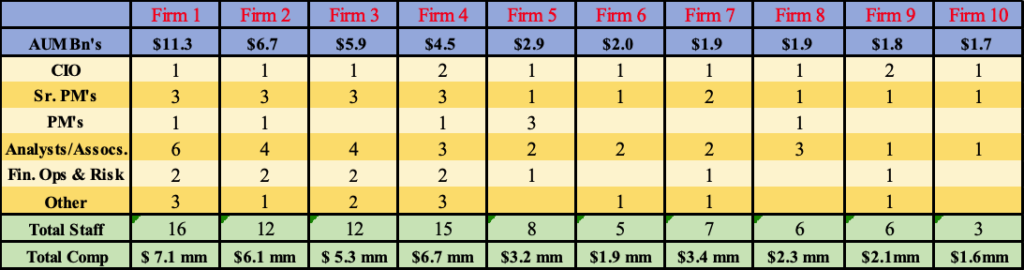
  • Appendix that lists 10 large E&F’s and provides $ AUM, Staff size, positions by job titles, and total team compensation for the Investment Office.

Ratio of In-House Staffing Relative to Size of Endowment/Corpus

The scatterplot below for 18 Non-Profits demonstrates two staffing clusters. $4 Bn+ AUM leads to in-house staffing of 10 -16 investment professionals and support staff. $1 Bn to $4 Bn AUM leads often to in-house staffing of 4-8 Investment professionals. The staff figures are almost exclusively investment professionals but there are some admin or shared resources as well.

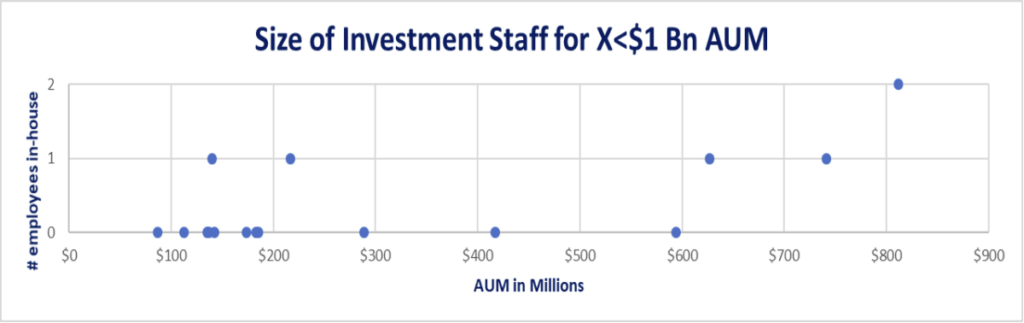
The scatterplot below for 17 Smaller Non-Profits demonstrates skeletal investment staffing:
Less than $1 Bn AUM leads to in-house staffing of 0-2 investment professionals and support staff.
Nearly half of the “0” in-house investment professionals reflects the adoption of either an OCIO
or Consultant Advisory model. What is striking is that there are two E and F’s in the $650-$750
mm AUM range that are a one-person “team.”

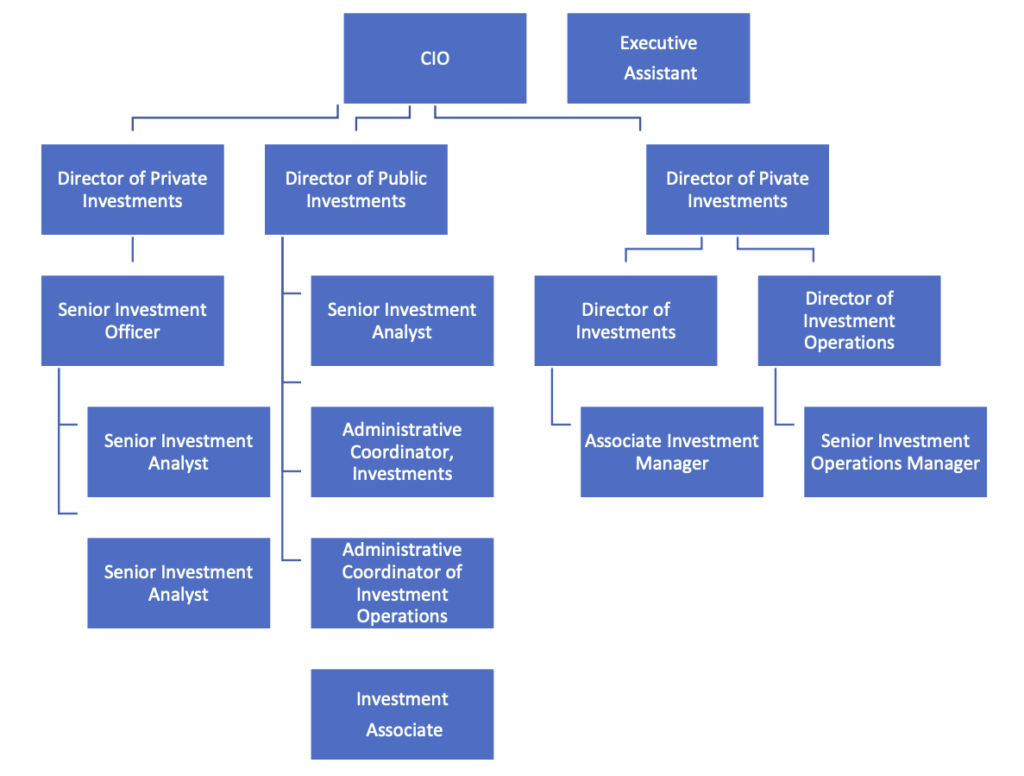
Sample Org Chart for approx. $11 Bn AUM

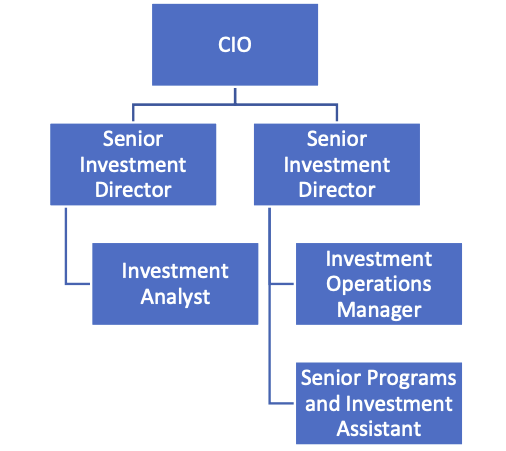
Sample Org Chart for $1.5 – $2 Bn AUM

Summary Table of all 35 E + F’s by AUM and In-House Staff Size

APPENDIX

The goal of this appendix is to provide the reader with the staffing (by category) for 10 large
Endowments or Foundations. The entities are ordered in descending $AUM size. All these E&F’s
have built and maintained in-house Investment Offices.
N.B. 2 entities (in the $750 mm – $1 Bn AUM range) opted recently to convert from in-house
Investment Office to adopt the OCIO model. This range appears to be the inflection point where
Boards/Committees struggle to decide what structure suits their organization best.
The total compensation by team is included as well. Do note that under the Other category, it
covers administrative roles that are not strictly investment-trained positions. Since they are
included on the public websites of these E&F’s as being members of the “Investment Office”, we
have opted to embrace this self-identification by the E&F’s.

Want to learn more? Please contact Chris Cutler, Tom Donahoe or Safia Mehta at 917 287 9551.

© 2019 MAS, LLC

TRANSITION TRAUMA – How To Avoid Losing Up To 1% of Your Portfolio

Virtually every large Outsourced CIO boasts a “dedicated onboarding” team. You will hear pleasant words like “seamless” and “facilitate” and “full transition takes 5 to 10 days.” This all
sounds so reassuring. As a Fiduciary, you can simply not rely on those “happy noises.”

Perhaps it is the number of moving parts, the reliance on a skeletal checklist, or the failure to
perform a simple “walk through” exercise that is the biggest culprit. When legal, operational or
IT roadblocks are not uncovered until the transition is underway, the likely result is economic
damage to your investment corpus.

A sample portfolio to transition might be:

  • 40% public equity securities
  • 20% fixed income securities
  • 15% Hedge Funds
  • 10% Private Equity
  • 5% Real Estate
  • 10% Cash

The simplistic view is hold onto to the cash, sell the liquid securities, and do the best you can
with the alternatives holdings. That approach glosses over some critical decision points:

  1. Proper sequencing of asset sales by asset class, date, and time.
  2. Not coordinating the timing of sales/buys to be synced to intraday/market close.
  3. Not factoring in the different settlement dates that vary by instrument and fund, e.g. mutual funds v. ETF’s v. security assets.
  4. Whether borrowing to facilitate the purchase of replacement assets is allowable.
  5. Whether futures/ETF’s could maintain needed market exposure and minimize the impact of settlement mismatches.
  6. Failure to minimize “time out of market” if that is your goal.
  7. No agreed timetable to perform a reconciliation or what constitutes “full” reconciliation.
  8. Decision to change asset allocations amidst the transition process itself.
  9. No clear game plan as to “care and feeding” of legacy assets.

Public Equities might be individual securities or held within mutual funds or ETF (Exchange
Traded Funds.) Each asset has its own settlement date as well as exit process. This means sales
timing issues and settlement issues. Public Equities may be sold intra-day (or MOC-market on
close, or VWAP-volume weighted average price.) Mutual funds pricing is at end of day, ETF’s
can be intraday or MOC and when you receive sales proceeds varies by instrument.

Hedge Funds are often liquidated only on a quarterly basis and there are typically holdbacks.
There may be investor-level or fund-level gates as well.

Private Equity has almost no liquidity and you may need to sell on a discounted basis in the
secondary market if you cannot wait the additional year(s) likely to full redemption. Legacy
assets require dedicated management and oversight.

When you change custodians, your existing custodian likely must follow up with phone calls
backs to authorized signatories. The signatories (Trustees) have busy lives and this further
restricts your flexibility to sell and buy at the best times to ensure a smooth transition. Beware
the vague or incomplete timetables or assurances that “we’ve been doing this a long time.” You
should require a daily update as to sales/proceeds and when/where these proceeds will be sent.

As part of our Outsourced CIO search services, we are also available to oversee the transition
process to ensure that your institution does not have gaps or additional market exposure during
the Outsourced CIO transition.

Want to learn more?

Please contact Chris Cutler, Tom Donahoe, or Safia Mehta, at 917 287 9551

©2019 MAS, LLC

580M Endowment Hires First CIO From Artisan Partners

By Aziza Kasumov August 19, 2019

“It’s common for universities to seek to hire in-house investment staff when their endowments grow to a certain size,” which Chris Cutler, founder of search firm Manager Analysis Services, previously pegged at between the $500 million and $1 billion range. (For example, Mount Holyoke College this summer conducted a search to hire its first CIO, after the school’s endowment grew to roughly $780 million in 2018, as reported.)

Insights into Outsourced CIO Searches

NonProfit News Excerpts (for release Sept 19)-Comments Tom Donahoe

Tell us how you became involved in Governance and guiding Outsourced CIO searches?

As an Executive Director of a Foundation, I personally directed a couple of outsourced CIO searches. The searches were both direct searches as well as searches conducted via an outsourced CIO search provider that the Foundation retained. This provided me direct experience with both approaches. The insights garnered from engaging directly in the step-bystep helps guide me as a search provider. Boards often need objective, independent guidance that help them optimize their investment decisions. These insights help animate our approach to achieving a successful OCIO search outcome for every client.

What is the typical catalyst for an Outsourced CIO search?

Board and Investment committee members are realizing that they just can’t do it themselves, they don’t have the bandwidth. There are many talented people on the committees and boards, but you only have a certain amount of a governance budget, i.e. the time and focus to fulfill your fiduciary duty. If the committee members quit their day jobs, they would certainly be able to undertake a full-blown search by themselves. But they realize that they can’t quit their day jobs, they meet 4X a year, and they can’t respond as nimbly as a fiduciary as they would like.

Any general observations on the search process itself?

A proper search effectively creates a long-term investment partnership for your client. We are trying to really understand the board, its investment philosophy and their specific goals and needs. We engage Board members directly and work with them to verbalize and document what their ideal would be. We then use their guidance to filter through the 70+ OCIO firms with a national reach (and regionals as well) to distill those providers to a group of five to 10 potential finalists. These are the providers who can do what is required, will align with the board’s goals, approach, and personality, and are not conflicted in any manner.

We work directly with committee members to review each potential provider from the filtered list. We understand what each firm offers, who could be an excellent match and who would work well with the committee to meet its needs and goals over any time horizon. The ideal outcome is that 5+ years in the future, the committee remains satisfied with the same outsourced CIO provider. Excellent performance helps but also the goals/philosophies remain well aligned.

When a firm is awarded the charge to become the outsourced CIO provider for an institution, we
are very much involved in the transition process. We continue our involvement over the first few quarterly meetings to monitor and make sure things are going the way they should and ensure assets were transferred properly. After a period of time, with the investment committee’s consent, we then step away because if we’ve done our job, the committee and provider should be well in sync with each other. There is a trend now, after a period of 3 to 5 years, for the endowment/foundation to request a formalized review of the OCIO provider. That can be done by the firm who originally did the search or alternatively by a different firm. It is an excellent fiduciary discipline.

Comments about fees…

There has been significant fee compression over the last several years. You’ve likely seen it in your own personal Vanguard or Fidelity account and the same thing is happening in the Outsourced CIO space as well. I believe that even if you do not perform a formal five-year review of you OCIO provider, you are well advised to checkup on fees periodically and what’s being charged on an annual basis. It is simply a prudent fiduciary discipline.

On the size and growth of the space…

Surveys often report $1.1 trillion in OCIO assets, others $1.4 trillion. Most surveys do indicate that the growth rate is slowing from the high teens to high single digits growth p.a. The OCIO model is satisfying a real need in the marketplace and fiduciaries are realizing that an Outsourced CIO provider can help compensate for the deficiencies in the governance budget.

Asset Transition between Providers

There is an important issue that I would like to surface and that is management of asset transition. As soon as you give notice to your current OCIO provider, saying you’re changing OCIO’s, it’s typically “pencils down” by the incumbent provider. They will respond to any questions you have, but there is no providing of new information and it’s not clear if portfolio rebalancing would occur during this interim period. From the old OCIO’s vantage point, they are now going to wait to hear how and when to transfer assets.

The transition period can be delayed or extended simply because the Investment Committee is organizing itself. During the transition process there can be slippage. That slippage could be 30 basis points on your entire portfolio, or it could be conceivably as much as 70 or 80 basis points when things are not going well. That is many multiples of the cost of doing a search itself.

When non-profits do an Outsourced CIO search, they don’t know the backstory for every organization. We differentiate ourselves in our intimate knowledge of these firms, who is in the driver’s seat, how long they are going to be there, what changes at the firm have occurred, and what are their motivations. We incorporate these insights in our conversations with the board so they best understand what each firm has to offer and to fully inform their decision making.

Why don’t we become an Outsourced CIO?

To provide added value as an investment manager, you need a critical mass to properly understand and monitor all the asset classes and best serve your client. There are great OCIO providers out there and we view our mission as achieving the best long-term fit for each of the non-profit and family office clients that we serve. Besides, we enjoy doing the searches, we enjoy the analysis, and we enjoy asking the questions and parsing out the answers. There is no better experience that matching a client with a well-suited OCIO provider who can provide the added value and support that our client needs and deserves.

Regrets of Investment Committees Upon Completing an OCIO Search

“We Looked at Too Many OCIO Providers” – The Endowment had $500 mm AUM and requested an RFP from 16 different firms. When they received back only 12 of the RFP’s, “it should have alerted us that we were not focused.” The Investment Committee Chair admitted later, they should have memorialized their investment priorities and spent more time filtering the available OCIO universe at the outset.

“We Included a Courtesy RFP for Our Local Bank” – This was embarrassing. Our bank knew us and scored high on their RFP back to us. In fact, they qualified as a finalist. When an IC member pointed out that their own $150 mm portfolio would double the bank’s AUM, the over concentration would be untenable. We had to explain, that after all the bank’s efforts, we could not even consider them. (An RFP typically requires 20 – 40 hours work to complete, with review by the OCIO’s internal compliance.)

IC Chair Did Not Recuse Himself from Review of an Insider Firm – While most IC members determined that they were comfortable with the process, the optics were poor. The IC Chair had insisted that a specific OCIO be included. The same OCIO managed the IC Chair’s own “friends and family” assets of $100 mm. The IC Chair actively participated in all discussions and voting. Moreover, the recommendation was written on his personal stationery and all communications were via his personnel email. There were no meeting minutes kept of the in-person review meetings with the OCIO candidate firms. There were additional indicia, but the reader can understand the concern by some IC members as to the appearance of a conflict.

OCIO Coverage Team Changed Within Months of the OCIO Hiring – The Investment Committee was severely disappointed when the “A” team moved from their account after 4 months. The college thought that they were continuing with the same team that had been so impressive in the bidding process but did not insert any provisions into the OCIO contract to ensure continuity of coverage.

Asset Transition Plan Was Not Detailed Nor Finalized – The incoming OCIO was charged with selling the assets. They sold them in timely fashion and then waited. After several weeks, the Investment Committee contacted them to receive an update as to the re-investment process. They were informed, things were fine. The OCIO had re-invested 15% of the portfolio and would ladder in over the next 5 to 6 months. Only then did the Foundation learn that the OCIO had an internal policy to “average into the market.” The OCIO said “not to worry” since there were no management fees incurred for monies while they remained “undeployed.”

Moral – If this is the first time that your Investment Committee is considering an OCIO, it’s critical that the planning be detailed and comprehensive. There are so many ways that value can be lost, or opportunities missed. Moreover, there are fiduciary concerns and conflicts of interest issues that may need specific focus at the outset.

Want to learn more? Please contact Chris Cutler, Tom Donahoe or Safia Mehta at 917 287 9551.

© 2019 MAS, LLC

Broad Study of Endowment Returns -NYU/GU – A Reasoned Response

WSJ: “Why Charities Have Been Such Bad Investors” – A Reasoned Response

An important new study of Endowment Investment Performance was released in Nov. 2018. Its two immediate lessons are: Don’t believe what you read about the “success” of large endowments’ strategies, and don’t trust self-reported performance numbers!

The authors found four key conclusions:

  1. Smaller endowments convincingly outperformed larger endowments in 2009-2016–This observation runs counter to the widely-held belief that sophisticated private strategies of larger endowments create an insurmountable advantage over smaller endowments.
  2. Actual IRS reported numbers fall well short of self-reported numbers in industry surveys–this observation creates broad questions about the integrity of data that is self-reported in compiling the NACUBO return benchmarks.
  3. “Investment wisdom of top universities is largely a myth” 2
  4. Higher fee investments have resulted in higher fees paid.

Smaller endowments have shown that with focus, proper dedication of internal resources, and intelligent outside advisory assistance, they can retain control over their endowments and get to a better investment destination.

When you get past the WSJ’s hyperbolic [click-bait] title, you’ll find a quite thoughtful study was performed on Endowment investment returns. The study finds “non-profits returned an average of 6.65% annually, even below [long -term] Treasuries” for the period 2009-16.

The study (first release) was created by two professors, one from Georgetown and the other from NYU. 3 The survey is important because of its large scale, 28,000 institutions. It’s based on actual IRS filings from 2009-16. Using submitted tax filings reveals dramatically less flattering results as compared to the self-reported returns of Endowments that form the basis of innumerable past industry surveys.

This response will provide you with the following:

a) A summary of the key conclusions of the professors’ work
b) Recommendations as to how the professors can strengthen/qualify their arguments.
c) Recommendations of additional cohorts and displays that will provide clarity for readers

While we feel that the professors arrived at quite logical conclusions, some of these are somewhat overstated. This weakens the persuasiveness and distracts from the overall usefulness of their study. While we are comfortable with the direction of the study’s findings, the methodology should be changed to better conform to actual investment industry practice. It remains an important study but is hampered, in its current version, by material over simplifications.

a) The study’s key conclusions (as quoted in the paper’s Abstract) are as follows:

  • “Endowments badly underperform market benchmarks”
  • “Smaller endowments perform better than larger ones”
  • “Higher education endowments, the majority of the $700 Bn asset class, do significantly worse than funds in other sectors”
  • The study finds mean returns of 6.65%, Long Term Treasuries 7.96% and US Equity 13.7% 4

We believe that these specific points are somewhat overstated. By revising some of the methodological approaches, the arguments can be made more compelling. By better reflecting actual market practices, the endowments’ underperformance will remain material but not as dramatic as the WSJ headlines would imply.

b) Recommendations to strengthen or qualify the study’s methods and conclusions:

  1. 2009-2016 return period covers only a rising market cycle not a complete cycle -comments Model portfolio composition should use the global equity ACWI and NOT the US S&P500.
  2. Observations on calculating approximate returns from the 990 tax filings.
  3. Present additional return tables that focus on the returns of Yale and other “Ivies”
  4. Competency of Investment Committees requires additional background and context
  5. High fees paid versus returns achieved should trigger review of structural governance conflicts


1) 2009-2016 RETURN PERIOD COVERS ONLY A RISING MARKET CYCLE

The time period was determined by the electronic data that the IRS released by court order. 5 It happens to cover the years of 2009-2016, which you, gentle reader, know coincided with a sustained bull market in US equity markets.

We must accept the time period selected. Going back further in history likely would mean that the IRS data would be both less accessible and less reliable. Moreover, only with the GFC (’07-’09) did many auditors prioritize testing of valuations of illiquid/structured investments. (Older data is more tenuous.) When we layer in a static asset allocation, as did the authors, we are dealing more in the academic world as opposed to a diversified portfolio that gets rebalanced over time. (see comments below.)

2) MODEL PORTFOLIO COMPOSITION – USE ACWI NOT S&P 500

The study used a model portfolio with the S&P500 Index as the exclusive equity index. This favors large cap and tech names, so growth and momentum strategies are rewarded. It also evidences a “home country” bias (USA) although more than 2/3 rd’s of world equity market values are outside the USA.

Moreover, endowment portfolios are built for perpetuity. So, a material percentage of the typical portfolio provides diversification and performance when equity markets are not performing as well. Finally, it is a static allocation that ignores diversification goals and simply cannot directly measure portfolio re-balancing effects.

The 60% S&P/40% Bond mix performed well. In fact, the Fed kept rates low (artificially) and engaged in quantitative easing. This also helped reduced volatility to quite low levels. In early 2019, we are only now observing more realistic levels of implied volatility in the markets. So, 2009-16 was a unique time.

To improve the analysis, we would recommend that reference index be recalculated using the MSCI ACWI in order to eliminate the home country bias as well as to better reflect a common benchmark used by Endowments. Certainly, since we do not have access to reliable, detailed asset allocation information (nothing GIPS compliant here but demonstrably more reliable than self-reported returns in industry surveys), so there are real data limits to the IRS numbers. Moreover, Fiscal year-end positions (on Form 990) could vary materially from those held intra-year.

3) CALCULATING APPROXIMATE RETURNS FROM THE 990 TAX FORM

The reality is that the 990 does not provide return numbers directly. Even if they did, one would have to determine whether it was a rigorous calculation. E.g. similar to a GIPS compliant standard. Given those impediments, the indirect calculations laid out in the paper make sense, given the limited information available. We have reviewed the methodology with auditors who specialize in the E and F space and they agree that calculating returns as outlined in the professors’ paper is a sound and highly defensible approach.

4) PRESENT TABLES TO HIGHLIGHT THE RETURNS OF YALE AND OTHER “IVIES”

For additional granularity, we recommend the authors add the following two tables to buttress their
conclusions:

  • YALE by itself
  • CHORT of all 8 Ivies Schools (and perhaps also just the 7 Ivies alone?)The existing cohort of top 20 (or so) Endowments while helpful, as presented, is subject to change given its link to US News rankings. Moreover, there is a dramatic difference in endowment size between number 20 ranked and the top 4 or 5 of the US News cohort.

Another benefit would be to highlight the difference between self-reported versus actual IRS 990 numbers. Finally, so much past ink has been spilled in tracking the Ivies’ performance that industry participants (as well as Boards) are very attuned to the Ivies’ performance returns and it is what the report’s audience would be quite keen to know.

5) IC GOVERNANCE ISSUES AS TO COMPETENCY

Staff/OCIO/Investment Specialists/Investment Committee (or a combination) could be the parties directing the actual asset allocations within an Endowment. Typically, there is no specific required background required to be an investment committee member. (Contrast with Audit Committees where the Chair is typically a CPA holder.) Given Board term limits, the composition of the Investment Committee could have changed materially during the study period.

There has been an explosion in the outsourced investment office model. Some surveys indicate that as much as 50% of Endowments between $25 mm to $500 mm in AUM have now adopted the outsourced model for part or all their total endowment management. Indeed, the actual investment decision-making process could have changed as well.

Many colleges allow Trustees to serve 7 – 9 years, some longer. This study covers 8 years and assuming staggered terms, well over ½ of the Investment Committee members could have changed. We do concede that the role of IC Chair does tends to be a role is held for an extended number of years. The more the actual IC compositions have changed during the study, the stronger is the authors’ argument that there is a material structural governance issue amongst Endowments.

6) HIGH FEES PAID FOR INVESTMENT ADVICE SHOULD TRIGGER DEEPER ANALYSIS

The paper’s authors point generally to high fees paid in some instances. This can occur when investments are directed specifically to high fee alternate investments. Many IC members work in the investment sector as professionals which the report points out is especially true for Endowments based close to financial centers. There is a common conceit to believe that since you do it for a living, you know better than your peers how it should be done. There are additional sources of dysfunction on IC committees (see Vanguard website for extensive research on the topic as well as recommended best practices.)

There is always the temptation to direct business to specific alternative investments or hedge funds that will provide additional fee income for those favored funds. One also has the issue of co-investments as well as excess business holdings where investments are concentrated in higher risk biotech start-ups or venture capital positions. That is beyond the scope of the authors’ paper and the writer mentions these situations simply to highlight their existence and potential impact on the returns that were observed in the study.

In summary, the study provides useful insight into a broad segment of the endowment investment market. The paper highlights some of the data deficiencies and approximations that exist given the crude structure of the IRS 990. There is less uniformity in reporting compared to other asset managers.

Given these material handicaps, the authors do succeed in shining much needed light into the vaguer corners of the endowment investment world. With the integration of the 6 recommended observations that are proposed, and the additional charts/tables as outlined, an updated version will attract more readers and advance the insights achieved by this study.

Want to learn more? Please contact Chris Cutler or Tom Donahoe.


Footnotes:

  1. Jason Zweig. “Why Charities Have Been Such Bad Investors.” Wall Street Journal 11/27/2018.
    https://www.wsj.com/articles/why-charities-do-goodbut-not-wellwith-your-money-1543402800
  2. Sandeep Dahiya, David Yermack. “Investment Returns and Distribution Policies of Non-Profit Endowment Funds.”
    Report 11/27/2018. Page 18 OR https://papers.ssrn.com/sol3/papers.cfm?abstract_id=3291117
  3. Ibid.
  4. Ibid., Page 3
  5. Ibid., Page 4

File Name — C: Governance – A Study of Endowment Returns: A Reasoned Response-

Multibillion E&Fs Struggle with Resource Limitations when Evaluating Managers

By Aziza Kasumov July 23, 2019

“If [the endowments] get bigger … is their staff going to continue to grow and grow and grow? That didn’t turn out to be the case,” Tom Donahoe, managing director of outsourced CIO (OCIO) search and governance at Manager Analysis Services, tells FundFire.

The size of an in-house investment office appears to have a “definite ceiling,” Donahoe and Chris Cutler, founder of Manager Analysis Services, write in the research paper.

Manager Analysis Services looked at 35 organizations, with assets ranging from $90 million to $11.3 billion, purposefully leaving out outliers such as the wealthiest Ivy League schools and other mega endowments. The firm also broke out the staff structure for the 10 largest endowments in its sample size, which revealed that even among in-house teams north of the $1.5 billion asset mark, resources might be tight.

…

Manager Analysis Services’ research also laid out sample organizational charts for endowments of varying asset sizes. An organization with around $11 billion in assets under management typically had a CIO, four or five people in senior management, two people in operations, and an executive assistant, says Donahoe. “That leaves you with … five people who are doing stock analysis, and they only have a certain bandwidth, as talented as they may be,” Donahoe says. “Even if you have this person on your staff, they’re not sitting there 40 hours a week analyzing managers,” he adds.

…

For both traditional and alternative managers, “this space is more limited then you might be thinking,” says Cutler. “If you’re a well-known name, you have a tremendous advantage,” he adds.

The limited resources may provide opportunities for OCIO providers to secure mandates from large endowments, according to the report, which notes that there’s a “tug of war” over whether in-house or OCIO works best in the $750 million to $1 billion AUM range. That asset range was much lower a couple of years ago and has steadily climbed up, both Cutler and Donahoe say.